Monday, July 21, 2014

CHITS: Charts In The Spotlight: Six Flags Entertainment (SIX): Support broke on disappointing sales despite inline earnings.

 
We've been watching this for a while as support was being tested.  Today, it broke on disappointing sales, though earnings were inline. 
Now what? 
Chat with us (use the "Chat" tool to the right on this blog page) and share your thoughts.


Please continue to visit Soos Global Market Musings for updates.

(Sign up to "Follow by Email"! And share with others!)

(Please note: This article is solely meant to be thought provoking and is not in any way meant to be personal investment advice. Each investor is obligated to opine and decide for themselves as to the appropriateness of anything said in this article to their unique financial profile, risk tolerances and portfolio goals).
Disclaimer: Please read and consider important information related to all communication made by Soos Global on this site by clicking here.
Additional Disclaimer: currently long many stocks/ETFs. Positions may change at any time without notice. 

Tuesday, July 15, 2014

CHITS: Charts In The Spotlight: CNK, GMF, DD, SIX

Fyi….Position update…..In addition to periodic global-macro posts to this blog, we occasionally share position updates that are routinely shared with our investors.  These comments are absolutely not meant to be investment advice and readers are reminded that all comments posted here are for information and entertainment purposes only!  Any commentary, especially those that include specific mentions of 'buying' or 'selling' or 'positions', is made solely for those limited informational and entertainment purposes, and NOT as advice.  While we will be sharing some detail on changes made to our portfolios, it's important to consider that our portfolio decisions are taken in a much broader context of our overall portfolio strategies and our assessment of each of our investor's unique financial profiles.  As such, what we do, and when we do it, is specific to our investor portfolios and is NOT intended, in any way, as advice for use by others.
With that in mind, we hope you find our comments of interest, and we'd be delighted to hear feedback!


(If you'd like to exchange thoughts on this post or on other subjects, please connect with me through the Private Chat tool on the right side of this page, or if you'd like to email thoughts, please do so through the Contact Form feature.  For public airings, please use the Comment feature below.  Looking forward to hearing your thoughts!)

Under the banner of "a picture tells a thousand words", here are a few things that we have under the hot lights.  


Please continue to visit Soos Global Market Musings for updates.

(Sign up to "Follow by Email"!  And share with others!)

(Please note: This article is solely meant to be thought provoking and is not in any way meant to be personal investment advice. Each investor is obligated to opine and decide for themselves as to the appropriateness of anything said in this article to their unique financial profile, risk tolerances and portfolio goals).
Disclaimer: Please read and consider important information related to all communication made by Soos Global on this site by clicking here.
Additional Disclaimer: currently long many stocks/ETFs, CNK.  Positions may change at any time without notice.   

Thursday, July 10, 2014

Soos Global Investor Portfolio Updates: AEO, DE, CAT, BTN

Fyi….Position update…..In addition to periodic global-macro posts to this blog, we occasionally share position updates that are routinely shared with our investors.  These comments are absolutely not meant to be investment advice and readers are reminded that all comments posted here are for information and entertainment purposes only!  Any commentary, especially those that include specific mentions of 'buying' or 'selling' or 'positions', is made solely for those limited informational and entertainment purposes, and NOT as advice.  While we will be sharing some detail on changes made to our portfolios, it's important to consider that our portfolio decisions are taken in a much broader context of our overall portfolio strategies and our assessment of each of our investor's unique financial profiles.  As such, what we do, and when we do it, is specific to our investor portfolios and is NOT intended, in any way, as advice for use by others.
With that in mind, we hope you find our comments of interest, and we'd be delighted to hear feedback!


(If you'd like to exchange thoughts on this post or on other subjects, please connect with me through the Private Chat tool on the right side of this page, or if you'd like to email thoughts, please do so through the Contact Form feature.  For public airings, please use the Comment feature below.  Looking forward to hearing your thoughts!)


Soos Global Investors:   Fyi…As I’ve indicated in recent missives, a number of factors, including sluggish economic growth, higher geopolitical risks, and markets’ beliefs that central bank rate hikes are coming soon, have made me increasingly defensive.  Today, we added another factor to the list by dusting off the European banking crisis issue “of old” (or more accurately, of “lurking beneath the surface”), as a Portuguese bank missed a debt payment and raised fears of a broader based banking problem.

The US markets responded as expected, selling off 180 points in early trading, but calm was seemingly restored later in the day, with the Dow closing down just 70 pts.  I’ll be watching closely to see how the Portuguese banking issue evolves in coming days and assessing how it will impact markets and asset valuations. 

In the meantime, below is a summary of some changes that I made to our portfolios today. 


1)      American Eagle Outfitters (AEO)….I exited from AEO today after the stock continued to trade poorly and on the heels of talk w/in the retail industry that “times remain tough”.  (Most notably, The Container Store chief yesterday noted that ‘the retail sector is in a funk’!).  The original investment premise on AEO was that the stock had already suffered due to the fickle teen  segment who had focused on discount/value buying from places like H&M rather than more upscale stores like AEO, but that AEO was adjusting its product offerings to win back that market share.  In addition, AEO was expanding overseas using a partner strategy in which the local partner would endure the heavy-lifting of the real-estate sites, and AEO would benefit from the licensing and product sales.  Along the way, however, the CEO left the firm, creating uncertainly which the market understandably didn’t like!  In addition, the teen segment continued to slow spending and to focus on discounters.  In a generally weak market, with an economy that is meandering along at roughly 2-2.5% GDP pace, I decided to step aside from AEO, cut our losses, and will continue to monitor its progress for possible re-entry down the road.  The enticing 4.4% dividend went ‘ex’ back on June 30, so we captured that payment.  Will revisit ahead of the next ex-date (and most likely after 30 days from today for the CORE taxable strategy, so that we book the tax loss).

2)      Deere (DE)….I had lightened up on DE a while ago in the mid-90’s, and exited the remaining position today at 88.54.  Following the June 30 Department of Agriculture Report which was quite bearish for agricultural commodity prices (having indicated far higher amounts of crop supply than had been anticipated), DE has struggled.  I still like Deere and would re-enter, but  I’m concerned that the recent pressure on farm equipment makers may persist.  In addition, I’ve continued to look for opportunities to shift the focus of one of our investment themes more towards the potential spending habits of the emerging middle class around the world, and to lighten up on the global emerging market infrastructure build.

3)      Caterpillar (CAT)….CAT has had a very strong run.  At current high levels, and with my defensive overall view on the economy, I exited CAT.  This is also in sync w/the shifting theme within the portfolios away from infrastructure and more toward emerging consumer middle class spending.  CAT faces increased competition around the world, and lots of the low hanging fruit that they were able to grab in recent years especially as Emerging Market countries were developing their infrastructures, is becoming more challenging to get at this time.  CAT does, however, remain a re-entry candidate at lower valuation levels.

4)      Ballantyne Strong (BTN)….I’ve started to lighten up on our position in this digital projector, lighting and computer display and servicing company.  It’s a very small company that I initially bought due to their growing business in digital theater projectors and screens.  Lots of theaters at this point, however, have already migrated to that new technology.  Even though BTN has worked hard to diversify their businesses, and I like their new focus, given my general concerns about the broader market facing headwinds which, as we saw today, could increase volatility that generally hits smaller cap companies more heavily, I’m looking to exit from the position and redeploy the capital elsewhere, while maintaining a foot in the theater play through our position in Cinemark.

As always, please email or call w/any questions or to discuss in more detail.
I’ll keep you posted.
Best,
Ed

Please continue to visit Soos Global Market Musings for updates.

(Sign up to "Follow by Email"!  And share with others!)

(Please note: This article is solely meant to be thought provoking and is not in any way meant to be personal investment advice. Each investor is obligated to opine and decide for themselves as to the appropriateness of anything said in this article to their unique financial profile, risk tolerances and portfolio goals).
Disclaimer: Please read and consider important information related to all communication made by Soos Global on this site by clicking here.
Additional Disclaimer: currently long many stocks/ETFs and BTN.  Positions may change at any time without notice.     


Wednesday, July 9, 2014

Are Rate Hikes Going to Pop the Equity Market (not yet a) Bubble?


(If you'd like to exchange thoughts on this post or on other subjects, please connect with me through the Private Chat tool on the right side of this page, or if you'd like to email thoughts, please do so through the Contact Form feature.  For public airings, please use the Comment feature below.  Looking forward to hearing your thoughts!)
 

FYI…I thought I’d share a few bigger-picture thoughts on issues that are serving as a backdrop to some portfolio shifts that I have under consideration. 


Fixed Income is not something that you’ve heard me talk much about for some time.  I have not had any in the strategies since yields had gotten too low to argue for a  good risk/return payoff.  Cash appeared to be the better option, leaving ‘powder’ dry to take advantage of equity market selloffs, either broad-based, or on selective issues.


Recently, especially with the improving US employment data, there’s increasing talk about the Fed’s targets on employment and inflation getting closer to being realized, and in turn, expectations are growing for a sooner-than-had-been-thought rate hike by the Fed.  As you can see in the following chart of 2yr Tsy yields, the rates have nearly doubled in recent weeks to approximately 0.50%.  One key issue worth considering is whether this is the beginning of a meltdown in the fixed income markets, which have been at historically low yields and tight spreads (especially high-yield) for quite a while, or whether the sell-off in fixed income and in turn the rise in rates will be limited by the automatic-stabilizer impact that higher rates will have on slowing the economy and taming inflation (if any).  Financial market literature and research is riddled with various versions of this debate.  Most notably, in my mind, is the recent introduction of a new term into the financial markets speak:  MACRO PRUDENTIAL POLICIES.  To be fair, it’s not entirely new in the academic literature, but for main-street-Wall-Streeters to be throwing around the term with seeming fluency, one has to take note.  In essence, Yellen, and Draghi, both went out of their way in speeches last week to counter the criticism laid upon them by the BIS who said that the overly easy monetary policies of central banks are setting the stage for another financial crisis as asset prices rise and bubbles ensue.  Yellen and Draghi countered by saying that rate hikes were too much of a ‘shotgun’ approach, and that in order to mitigate systemic risk of financial instability, central banks have to use targeted, rifle-shot macro prudential policies (code for regulations, supervision, stress tests, capital levels, etc). 

(Cont’d below….)


The focus at this point has to be on just how far Yellen and Draghi go into turning the rhetorical battle into actual practice.  To be sure (or as sure as one can be) continuation of the Fed’s tapering is widely anticipated and, as I mentioned, the timing of the Fed’s first rate hike has also been brought forward.  But the Fed is well aware of the impact that higher rates has on the economy, witnessing the slowdown in the housing sector that we saw since last year when long rates and mortgage rates climbed.  That, in and of itself, may be the limiting factor in keep the Fed from raising rates too far too fast.  Likewise, on the long-end of the curve, higher long-term rates wouldn’t be surprising, but just how far long rates climb is likely to be tempered by an environment of relatively slow economic growth (for ’14, trend growth in the US of roughly 2.0-2.5% is still a wished-for outcome!) and minimal signs of inflation (though rising oil, food and other commodity prices have to be watched closely).


We started this year with 10yr yields closer to 3.0%, and as they’ve fallen, equities have continued their rise to historic highs (see first chart below).  We also have a situation where, from a valuation perspective, equities are not quite yet in nose-bleed territory, but they’re not far from it! (see second chart below from DecisionPoint on StockCharts.com which shows where the S&P would be priced based on trailing 12-mth earnings at various P/E ratios.  It shows current actual S&P levels at near 20x, which has historically been considered the ‘overvalued’ zone).


From a strategies perspective, I’m remaining defensive on equities, taking profits on some positions that appear to have overstretched, but continuing to look for seemingly oversold opportunities in the market to add to our positions.  If the markets continue to take short rates higher, I will be looking to add short term investment grade corporate bonds if they appear to be oversold. 

In coming days, I’ll be updating more specifics on individual assets and on other portfolio considerations.  Stay tuned….

Best,

Ed

Please continue to visit Soos Global Market Musings for updates.

(Sign up to "Follow by Email"!  And share with others!)

(Please note: This article is solely meant to be thought provoking and is not in any way meant to be personal investment advice. Each investor is obligated to opine and decide for themselves as to the appropriateness of anything said in this article to their unique financial profile, risk tolerances and portfolio goals).
Disclaimer: Please read and consider important information related to all communication made by Soos Global on this site by clicking here.
Additional Disclaimer: currently long many stocks/ETFs.  Positions may change at any time without notice.     


Tuesday, July 8, 2014

"CHITS": Charts In The Spotlight: DuPont (DD)..are the ill-effects of the "surprise" waning?

(If you'd like to exchange thoughts on this post or on other subjects, please connect with me through the Private Chat tool on the right side of this page, or if you'd like to email thoughts, please do so through the Contact Form feature.  For public airings, please use the Comment feature below.  Looking forward to hearing your thoughts!)
We first shined our spotlight on DuPont (DD) in our posting last week that noted how well the market had anticipated the company's "surprise" earnings announcement in which they lowered guidance for both Q2 and the full year.   We struggled to mute our cynicism at how the market had sold off DD both in relation to the broader market and within its sector for three weeks leading up to the company's "surprise".  
Since then, we've been shining the hot-lights on the company's performance and have updated our notations on the chart below.
Is DD bottoming?  Is momentum turning up?  Is it currently or soon-to-be 'oversold'?
Worth watching closely.
We currently have no position of DD in our strategies, but these are among the questions that we're considering as we head into earnings season, and especially as the market is coming off recent highs.


Will keep you posted.
Ed

Please continue to visit Soos Global Market Musings for updates.

(Sign up to "Follow by Email"!  And share with others!)

(Please note: This article is solely meant to be thought provoking and is not in any way meant to be personal investment advice. Each investor is obligated to opine and decide for themselves as to the appropriateness of anything said in this article to their unique financial profile, risk tolerances and portfolio goals).
Disclaimer: Please read and consider important information related to all communication made by Soos Global on this site by clicking here.
Additional Disclaimer: currently long many stocks/ETFs.  Positions may change at any time without notice.     


Monday, June 30, 2014

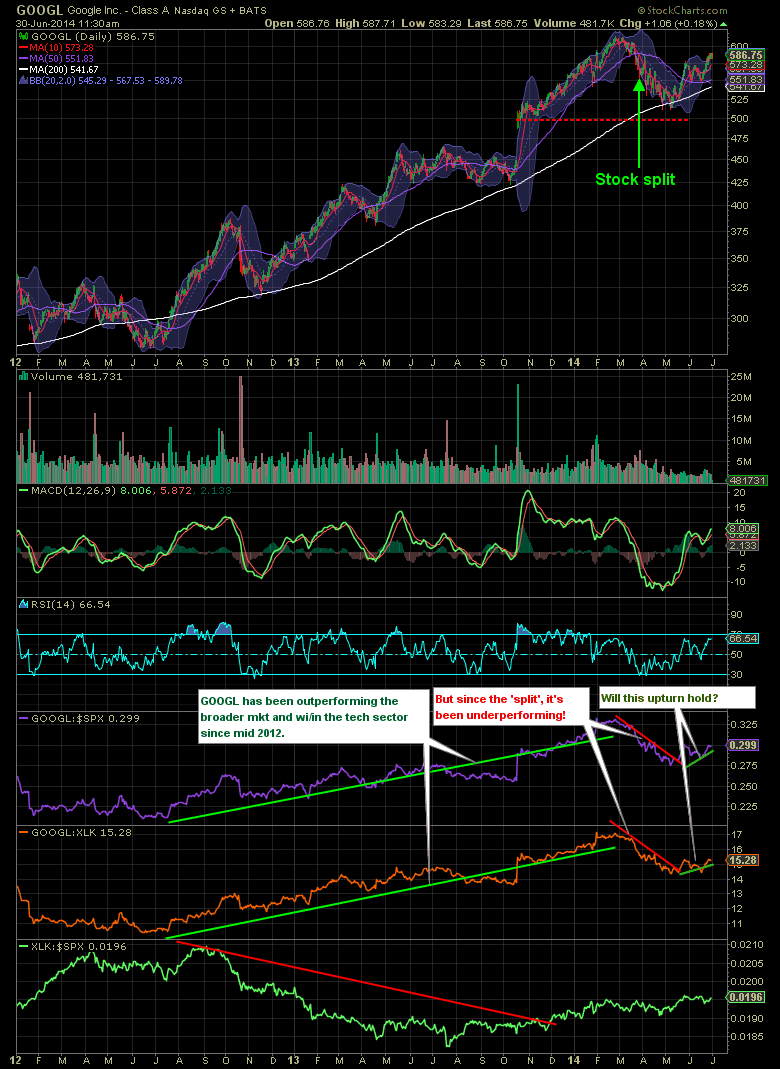
"CHITS" Charts In The Spotlight: Google (GOOGL)...will the upturn hold?

(If you'd like to exchange thoughts on this post or on other subjects, please connect with me through the Private Chat tool on the right side of this page, or if you'd like to email thoughts, please do so through the Contact Form feature.  For public airings, please use the Comment feature below.  Looking forward to hearing your thoughts!)
"CHITS": Charts in the Spotlight: Google ($GOOGL)...will the upturn hold?.


We currently have no position in GOOGL, but we're watching it.  GOOGL's diversification into all kinds of businesses from semiconductor manufacturers to alternative energy companies is compelling.  Valuation, however, needs to be considered on an ex-emotional-market-hype basis!  Tough assignment....
Will keep you posted.
Ed


Please continue to visit Soos Global Market Musings for updates.

(Sign up to "Follow by Email"!  And share with others!)

(Please note: This article is solely meant to be thought provoking and is not in any way meant to be personal investment advice. Each investor is obligated to opine and decide for themselves as to the appropriateness of anything said in this article to their unique financial profile, risk tolerances and portfolio goals).
Disclaimer: Please read and consider important information related to all communication made by Soos Global on this site by clicking here.
Additional Disclaimer: currently long many stocks/ETFs.  Positions may change at any time without notice.     

M&A and Buybacks: Two fuels to the market fire that may be drying up....

Something to think about as we’re counting down to the upcoming fireworks:  Buybacks and M&A. 

In truth, “dry up” is a bit strong, especially for the M&A driver of markets, since large deals continue apace and until the ‘inversion’ motivation is mitigated, one would expect more and more companies to find ways to seize the tax advantage (US labor/economy disadvantage) of acquiring and domiciling overseas.  The slowing is more likely to come from valuations that are making deals less compelling.

But the Buyback craze is seemingly slowing, certainly as judged by rhetoric from CEOs.

Both articles below are a worthy reads on the respective subjects, and ought to raise a caution flag at a time when markets are still at/close to all-time highs!  (See chart below…a little reminder of where S&P has been over the past 20 years!)


Fyi….
Ed
Please continue to visit Soos Global Market Musings for updates.

(Sign up to "Follow by Email"!  And share with others!)

(Please note: This article is solely meant to be thought provoking and is not in any way meant to be personal investment advice. Each investor is obligated to opine and decide for themselves as to the appropriateness of anything said in this article to their unique financial profile, risk tolerances and portfolio goals).
Disclaimer: Please read and consider important information related to all communication made by Soos Global on this site by clicking here.
Additional Disclaimer: currently long many stocks/ETFs.  Positions may change at any time without notice.